Quick answer (updated October 2026): TCS on a gift to your son in the USA (or daughter) is collected by the Indian bank under LRS: nil on the first ₹10 lakh a parent remits in a financial year, and 20
Quick answer (updated October 2026): You can sometimes wire money from India to escrow, especially gift funds, since Fannie Mae allows donors to transfer gifts directly to the closing agent. But funds
Quick answer (updated October 2026): Seasoned funds from India are funds that already sit in your US account for the full statement period your lender reviews. For a purchase, Fannie Mae asks for stat
Quick answer (updated October 2026): The foreign assets mortgage Fannie Mae rule (Selling Guide B3-4.2-05) says money from abroad used for your down payment, closing costs or reserves must be exchange
Quick answer (updated October 2026): An NRE account down payment is one of the easiest ways to bring money from India: NRE balances are freely repatriable. The catch is on the US side. Funds must be c
Quick answer (updated October 2026): For a 15CA 15CB down payment transfer, Form 15CA is the online declaration the remitter files before money leaves India. Remittances up to ₹5 lakh in a financial y
Quick answer (updated October 2026): To sell property in India and buy a house in the US, start at least 90 to 120 days before you need the funds. The sale proceeds go through TDS, land in your NRO ac
Quick answer (updated October 2026): This visa mortgage eligibility chart shows the pattern: every lawfully present non-permanent resident can use conventional loans on the same terms as citizens unde
Quick answer (updated October 2026): You can buy a house while your spouse waits for a visa by qualifying on your income alone. Your spouse doesn't need to be on the loan, but in community property st
Quick answer (updated October 2026): H-1B stamping before closing is risky because a 221(g) administrative processing delay has no fixed end date. If you must travel, lock a rate long enough to cover
Quick answer (updated October 2026): Does buying a house affect your green card case? For H-1B and L-1 holders, generally no: both are "dual intent" categories, so showing ties to the U.S. isn't held
Quick answer (updated October 2026): An asylum EAD mortgage depends on which stage you're in. Granted asylees and admitted refugees can generally get conventional loans and qualify as "qualified alien
Quick answer (updated October 2026): Yes, an expired green card mortgage is usually doable. Permanent resident status doesn't expire when the card does. Since September 2024, an I-90 receipt notice ex
Quick answer (updated October 2026): A conditional green card mortgage works much like any permanent resident loan. Conditional residents are lawful permanent residents under immigration law, so conve
Quick answer (updated October 2026): With an I485 pending mortgage application, lenders classify you as a non-permanent resident until USCIS approves your green card. Conventional loans are available
Quick answer (updated October 2026): Down payment assistance for green card holders is widely available because most state programs accept permanent residents, either directly or by following the unde
Quick answer (updated October 2026): Cary NC homes for Indian families usually mean new construction in Morrisville, Apex or west Cary, financed with a conventional loan under the 2026 $832,750 baseli
Quick answer (updated October 2026): Redmond home buying on an H-1B is still possible in late 2026. The Labor Department's PERM pause affects green card timing, not your H-1B status or conventional lo
Quick answer (updated October 2026): In the co-op vs condo Queens decision, a co-op means buying shares in a corporation that must approve you through a board package and interview, often with strict
Quick answer (updated October 2026): To buy a house in Edison NJ, expect a signed contract followed by a three-business-day attorney review, property taxes that weigh heavily on your debt-to-income ra
Quick answer (updated October 2026): In Frisco and Prosper, a PID is a fixed assessment tied to your lot that you pay in installments or can often pay off, while a MUD is a tax rate applied to your ho
Quick answer (updated October 2026): MUD tax in Katy, Sugar Land and Pearland is a separate property tax levied by a municipal utility district to repay bonds for water, sewer and drainage. It goes in
Quick answer (updated October 2026): The mortgage interest deduction for H-1B holders works the same as for citizens once you are a US resident alien for tax purposes, usually by passing the substanti
Quick answer (updated October 2026): Closing while out of country is possible through a power of attorney, a mail-away closing notarized at a US embassy or consulate, or in some cases a remote online
Quick answer (updated October 2026): An appraisal gap is the difference between your contract price and a lower appraised value. Lenders base your loan-to-value on the lower of the two, so the gap com
Quick answer (updated October 2026): The most important questions to ask a mortgage lender on a visa are whether they add overlays beyond Fannie Mae and Freddie Mac rules, such as minimum visa validit
Quick answer (updated October 2026): The mortgage preapproval documents a visa holder needs are the standard income, asset and credit documents every borrower provides, plus proof of lawful presence:
Quick answer (updated October 2026): A name mismatch between your passport, Social Security record and credit report won't automatically block a mortgage, but it must be explained and sometimes fixed.
Quick answer (updated October 2026): Don't open a credit card before a mortgage application or during the loan process. New cards add hard inquiries that underwriters ask about, can raise reported bal
Quick answer (updated October 2026): Mortgage rate shopping has a small, contained effect on your credit score. FICO typically treats multiple mortgage inquiries within a short window (45 days in newe
Quick answer (updated October 2026): For an authorized user mortgage file, the account usually helps your credit score, and Fannie Mae's DU considers authorized user tradelines in its risk assessment.
Quick answer (updated October 2026): Rent reporting can help a mortgage application in two separate ways. Reported rent can add a tradeline that newer scoring models such as VantageScore 4.0 may use.
Quick answer (updated October 2026): Amex global transfer from India can help you get a US American Express card quickly using your Indian Amex account history, but that history does not appear on you
Quick answer (updated October 2026): Delayed financing is a Fannie Mae exception that lets you buy a home with cash, then take a cash-out refinance within six months without waiting the usual seasonin
Quick answer (updated October 2026): In the 15 vs 30 year mortgage decision, the 15-year saves a lot of interest but raises your payment sharply. On a \(480,000 loan at October 2026 average rates, the
Quick answer (updated October 2026): Whether to pay off your mortgage early or invest comes down to three things: your mortgage rate versus your expected after-tax investment return, how much liquidit
Quick answer (updated October 2026): Yes, a cash out refinance visa holder loan is available on conventional terms. Fannie Mae allows non-permanent residents the same terms as citizens, up to 80% LTV
Quick answer (updated October 2026): Yes, you can buy a fourplex with 5 percent down. Fannie Mae and Freddie Mac allow up to 95% LTV on owner-occupied 2-4 unit homes, as long as you live in one unit.
Quick answer (updated October 2026): A non warrantable condo is a unit in a project that doesn't meet Fannie Mae or Freddie Mac project standards, so it can't get a standard conventional loan. Common
Quick answer (updated October 2026): If your new construction visa expire date falls before completion, what matters is your status and documents at closing, not at contract. Fannie Mae sets no minimu
Quick answer (updated October 2026): You don't have to use a builder preferred lender. Under RESPA's affiliated business rules, a builder must disclose its lender relationship and generally can't requ
Quick answer (updated October 2026): A 2-1 buydown lowers your rate by 2% in year one and 1% in year two, then returns to the full note rate. A permanent builder rate buydown lowers the rate for the l
Quick answer (updated October 2026): In the ARM vs fixed H-1B decision, the right choice depends on how long you will keep the loan, not how long you'll keep your visa. A 5/6, 7/6 or 10/6 ARM fixes th
Quick answer (updated October 2026): An 80 10 10 loan splits your financing into a first mortgage for 80% of the price, a second mortgage or HELOC for 10%, and a 10% down payment. It can avoid PMI, or
Quick answer (updated October 2026): No, not on a standard conventional loan. Visa holder mortgage rates on Fannie Mae and Freddie Mac loans are priced on credit score, loan-to-value, occupancy, prope
Quick answer (updated October 2026): An H1B 30 percent down payment is not a Fannie Mae or Freddie Mac requirement. Both treat lawful non-permanent residents like US citizens, so conventional minimums
Quick answer (updated October 2026): A jumbo loan on an H1B is available from many lenders, but rules vary by investor because jumbos aren't bought by Fannie Mae or Freddie Mac. Any loan above your co
Quick answer (updated October 2026): How to hold title as a married couple depends on your state. Common choices are joint tenancy with right of survivorship, tenants in common, community property (in
Quick answer (updated October 2026): Estate tax rules for a house with a non-citizen spouse are different. The unlimited marital deduction generally isn't available when the surviving spouse isn't a U
Quick answer (updated October 2026): In Texas, a community property spouse must sign the mortgage's security instrument on a homestead even if they're not a borrower. Texas Family Code Section 5.001 s
Quick answer (updated October 2026): To use a power of attorney from India for a US closing, get your lender's and title company's approval first, then sign a specific POA naming the property and loan
Quick answer (updated October 2026): You can buy a house before marriage solo or with your fiancé as a co-borrower. Fannie Mae allows a fiancé to gift down payment funds. A home bought before marriage
Quick answer (updated October 2026): If you're getting married during the mortgage process, tell your loan officer right away. Your marital status on the 1003 must be updated, and your spouse's debts
Quick answer (updated October 2026): If your parents are on a visitor visa living with you for months at a time, your home is still your primary residence and your mortgage isn't affected. Parents on
Quick answer (updated October 2026): You can buy a house with your sibling on one conventional mortgage. Both of you sign the note, so each of you is liable for the full payment, not half. Lenders com
Quick answer (updated October 2026): A startup founder mortgage hinges on one number: your ownership. At 25% or more, lenders treat you as self-employed and generally want a two-year history of stable
Quick answer (updated October 2026): A motel owner can buy a house even with no rent history from living in the manager's quarters. Fannie Mae doesn't require a rental history, so lenders typically wa
Quick answer (updated October 2026): A restaurant owner mortgage can only use income a lender can document. Cash that never hits your tax return or your bank account can't count, no matter how busy th
Quick answer (updated October 2026): A franchise owner mortgage is underwritten as self-employed income when you own 25% or more. Lenders review each store entity's tax returns, add back depreciation
Quick answer (updated October 2026): A pharmacist mortgage depends on how you're paid. Employee pharmacists qualify on W-2 base pay, with overtime and shift differentials averaged over two years. Inde
Quick answer (updated October 2026): In a dentist mortgage, a practice loan that shows on your personal credit can be excluded from your debt-to-income ratio if your practice has paid it for at least
Quick answer (updated October 2026): Yes, you can usually close a physician mortgage on an employment contract before your attending job starts. Conventional loans allow it under Fannie Mae's offer-le
Quick answer (updated October 2026): A physician loan on an H-1B is possible, but not universal. Physician mortgage programs are lender-specific portfolio products, and many exclude or restrict non-pe
Quick answer (updated October 2026): An H-1B consultant mortgage works like any W-2 mortgage. If your consulting company issues your W-2 and runs payroll, that company is your employer, not the client
Quick answer (updated October 2026): Bonus income counts for a mortgage when you can show a history of receiving it. Fannie Mae recommends two years but accepts no less than 12 months with offsetting
Quick answer (updated October 2026): Yes, you can get a mortgage with an offer letter. Fannie Mae's Selling Guide B3-3.3-03 (updated October 7, 2026) allows two paths: one where the lender gets your f
Quick answer (updated October 2026): A pledged asset mortgage lets you pledge part of your investment portfolio as extra collateral instead of selling it for a down payment. Your shares stay invested
Quick answer (updated October 2026): An RSU down payment works well if you document it. Lenders accept vested shares via brokerage statements; if the shares are worth at least 20% more than you need,
Quick answer (updated October 2026): A 401(k) loan for a down payment lets you borrow up to the lesser of $50,000 or 50% of your vested balance, tax-free if repaid, and Fannie Mae doesn't require the
Quick answer (updated October 2026): Yes, a gift from an uncle for a mortgage is generally acceptable on a conventional loan. Fannie Mae's Personal Gifts rule (updated February 4, 2026) allows gifts f
Quick answer (updated October 2026): EPF withdrawal as an NRI changed under the EPF Scheme 2026, notified June 29, 2026. Full withdrawal is allowed on permanent migration abroad; otherwise you general
Quick answer (updated October 2026): Hawala money and a mortgage don't work together because lenders must document where every dollar of your down payment came from, and hawala or hundi transfers leav
Quick answer (updated October 2026): You can send money from Bangladesh to USA for a house, or from Nepal, if it moves through a formal bank channel and every step is documented. Lenders need a gift l
Quick answer (updated October 2026): You can send money from Pakistan to USA for a house down payment, but the lender must be able to trace every rupee. Use a bank wire (a Roshan Digital Account is cl
Quick answer (updated October 2026): You can sell gold for a down payment. Fannie Mae allows proceeds from selling personal assets, but you'll need proof of ownership where possible, a bill of sale or
Quick answer (updated October 2026): On agency loans, foreign assets as mortgage reserves usually have to follow Fannie Mae's foreign asset rule: converted to dollars and held in a US or state-regulat
Quick answer (updated October 2026): Your lender doesn't receive your FBAR, which is filed with FinCEN, not with your tax return. But an FBAR mortgage question still matters: foreign accounts can surf
Quick answer (updated October 2026): You file Form 3520 for a gift from parents abroad when gifts from nonresident alien individuals total more than $100,000 in a tax year. Gifts from related people,
Quick answer (updated October 2026): An H-1B extension pending mortgage is possible. Fannie Mae and Freddie Mac set no minimum visa validity, so a timely filed extension with an I-797C receipt can sat
Quick answer (updated October 2026): Yes, an expired visa stamp mortgage is usually fine. The visa stamp in your passport is for entering the US; your I-94 record and I-797 approval show your current
Quick answer (updated October 2026): You can change jobs on an H-1B during a mortgage, but timing decides whether it's a non-event or a lost house. AC21 portability lets you start once the new petitio
Quick answer (updated October 2026): A cap exempt H1B mortgage follows the same Fannie Mae and Freddie Mac rules as any H-1B loan: non-permanent residents qualify on the same terms as citizens, and FH
Quick answer (updated October 2026): A J1 waiver physician mortgage is usually a conventional loan or a physician loan from a lender that accepts H-1B borrowers. Conrad 30 doctors work on H-1B status,
Quick answer (updated October 2026): A TN visa mortgage is usually a conventional loan. TN professionals are non-permanent residents, so Fannie Mae and Freddie Mac allow financing on the same terms as
Quick answer (updated October 2026): An O1 visa mortgage works like any non-permanent resident loan: Fannie Mae and Freddie Mac allow conventional financing on the same terms as citizens, and FHA is n
Quick answer (updated October 2026): Yes, H-4 EAD income can count toward a mortgage. Fannie Mae treats it like any other wage income: a two-year history is recommended, and at least 12 months can wor
Quick answer (updated October 2026): A cap gap mortgage is possible. If your H-1B change-of-status petition was timely filed, your F-1 status and work authorization extend automatically, now through A
Quick answer (updated October 2026): A STEM OPT mortgage is usually a conventional loan, since FHA is closed to non-permanent residents. Fannie Mae sets no minimum remaining work-authorization period,
Quick answer (updated October 2026): Yes, a mortgage on OPT is possible. Fannie Mae and Freddie Mac let lawfully present non-permanent residents borrow on the same terms as citizens, so an OPT EAD hol
Quick answer (updated October 2026): FIRPTA matters when selling a house after moving to India only if you're a "foreign person" (a nonresident alien) at the time of sale. Then the buyer generally wit
Quick answer (updated October 2026): "Non recourse states mortgage" protection means that in some states, and for some loans, a lender can't pursue you personally for the shortfall after foreclosure.
Quick answer (updated October 2026): The best FHA alternative for H-1B buyers is usually a conventional loan. Fannie Mae allows 3% down for first-time buyers (or HomeReady within income limits), 5% do
Quick answer (updated October 2026): A no credit score mortgage in 2026 is possible through Fannie Mae. For Desktop Underwriter casefiles created on or after November 16, 2025, Fannie no longer sets a
Quick answer (updated October 2026): An EAD renewal pending mortgage file is riskier than it was a year ago. For renewals filed on or after October 30, 2025, the 540-day automatic extension no longer
Quick answer (updated October 2026): For most borrowers, the $100K H-1B fee has no effect on mortgage approval. The proclamation targeted new petitions for workers outside the US, not extensions, chan
Quick answer (updated October 2026): If you're laid off on an H-1B with a mortgage, the loan does not become due because your visa status changes. You still owe the payments wherever you live. Your re
Quick answer (updated October 2026): The H-1B grace period mortgage worry is real but premature. USCIS proposed eliminating the 60-day grace period on September 11, 2026; it is not final. Your mortgag
Quick answer (updated October 2026): An I-140 approved mortgage file isn't required by Fannie Mae or Freddie Mac, which lend to H-1B holders on the same terms as citizens. But an approved I-140 can ma
Quick answer (updated October 2026): Yes, in most cases. The PERM freeze mortgage question comes down to this: a paused labor certification does not change your current H-1B status, and Fannie Mae and
Dallas is the second-largest Indian-American metropolitan area in the country, with roughly 270,000 people, behind New York and just ahead of San Francisco's 260,000. That is Pew Research's 2023 data,
Your principal and interest are fixed for thirty years. Your total monthly payment is not, and in Texas the second year is where that distinction stops being theoretical.
The call we get every January
Start with the disclosure that belongs at the top rather than buried in a footer: Masala Loans does not originate Sharia-compliant home financing contracts. This post is educational. It is not an offe
Zillow will tell you the roof age, the HVAC install year, the elementary school rating and the exact square footage of the third bedroom. It will not tell you which way the front door faces. Neither w
The purchase contract your agent sends over has a blank line near the top for the closing date. Most buyers let the agent fill it in — thirty days out, forty-five if the loan is complicated. If your f
The gift letter has one line in it that does all the work: the donor states that no repayment is expected.
Not "repayment is flexible." Not "repayment when you are able." No repayment is expected, in
"My parents want to be on the house."
We hear that sentence several times a week, and it means at least three different things depending on who is saying it. Before anyone signs anything, separate the
The common belief is that if your parents are moving in with you and helping with the down payment, their money is complicated. Foreign account, no US income, they will be living in the house — surely
A cousin doing his master's at UT Dallas has been paying you $800 a month for the front bedroom for the last year and a half. He pays by Zelle, on the third, every month. You are buying a house and yo
Ten. That is the ceiling, and it is written down: Fannie Mae's Selling Guide B2-2-03 says DU allows a maximum of 10 financed properties for second home and investment borrowers.
Almost nobody in our m
The question arrives in the same shape every time, usually from somebody whose brother-in-law already did it. Can I just buy the rental in my LLC? And the answer depends entirely on which lender you a
A loan that does not ask for your income sounds like 2006. That instinct is healthy, and most borrowers who hear about DSCR financing for the first time have exactly that reaction: this is how the las
Take Arun, a composite of files we see in Katy. He earns \(132,000 a year as an engineering manager, his own house carries a \)3,600 payment, and he has a car note and a student loan. He found a $320,
DSCR stands for debt service coverage ratio, and the entire loan program rests on one line of arithmetic:
DSCR = gross monthly rent ÷ PITIA
PITIA is principal, interest, taxes, insurance, and associat
Every Diwali party has the one uncle who says it with total confidence. Beta, you can't own rental property on an H-1B. They'll cancel your visa. He has been saying it for a decade, and he is wrong.
H
Four families own a restaurant together. Each put in a quarter of the capital, one of them runs it day to day, the other three show up on weekends and look at the numbers once a quarter. Everybody get
$6,000.
That is the number at which your bank statements start generating homework, if your qualifying income is \(12,000 a month. Not \)10,000. Not the $10,000 currency transaction reporting figure e
Look at the top of your contract. If it says "corp-to-corp" or "C2C," your mortgage file just got three times longer than your colleague's, and the two of you make exactly the same money doing exactly
The SBA 504 program will not fund working capital. It will not fund inventory. And it explicitly excludes "speculation or investment in rental real estate."
That last phrase has killed more hotel deal
Two loans. Two underwriters. Two sets of paperwork. Almost nothing carries from one file to the other, and the fastest way to lose three weeks is to assume it does.
You bought the station with a comme
Fourteen months is not two years, and the general expectation in conventional underwriting is two years. That is the honest starting point, and any loan officer who tells you otherwise without asking
"We need two years of tax returns." Every self-employed borrower in America has heard that sentence, usually delivered as though it were carved into a wall somewhere. For a large number of the busines
Pull out your Schedule C. The one your CPA filed, the two-page form attached to your 1040, with "Profit or Loss From Business" across the top.
Most business owners read one number on it: line 31, net
Twelve or twenty-four. That is the first decision in a bank statement file, and it moves the qualifying income more than almost anything else you will do.
A bank statement loan does not read your tax
Your CPA did exactly what you hired her to do. Depreciation on the coolers and the fuel dispensers. Business use of the home office. Amortization on the goodwill you paid for when you bought the store
PUBLISHER NOTE: Apurva — this draft intentionally omits specific dollar caps for the 203(k) Limited program and the exact renovation-cost threshold that triggers a required HUD consultant, because nei
PUBLISHER NOTE: Apurva — this draft deliberately contains no county-specific FHA limit figures, because per-county numbers were not in the verified fact pack. Before publishing, pull the current 2026
A borrower called us in August with a printed amortization schedule and a highlighted row. He had reached 78% of his original purchase price, four years into an FHA loan, and wanted to know where to s
At a 740 credit score, conventional usually wins. Not always, and not by a trivial margin either way, but usually — and the reason is structural rather than a matter of shopping harder. FHA charges ev
Take your green card out of your wallet and turn it over. The back carries the card number and the machine-readable band, and an FHA underwriter is going to ask for both sides of it. That is not paper
"Who pays closing costs" is one of the most searched real estate questions in the country, and the honest answer annoys people: mostly, whoever the contract says.
Very little of what you will hear des
Your offer gets accepted on a Tuesday. On Wednesday your agent asks you to deliver a check for $10,000, made out to a title company you have never heard of, within three days. Nobody has explained who
$832,750.
That is the 2026 baseline conforming loan limit for a one-unit property, announced by the Federal Housing Finance Agency on November 25, 2025. It is up $26,250 from 2025, an increase driven
Somewhere in your closing package is a one-page private mortgage insurance disclosure with two dates printed on it. Most buyers sign it, file it, and never look at it again. Those two dates are the on
Three percent down is real. The income cap attached to it is the part that never makes it into the WhatsApp forward.
HomeReady, Fannie Mae's low-down-payment program, and Home Possible, Freddie Mac's
Thirty-two thousand rupees leaves your account on the fifth of every month, and has since 2019. It is the education loan your father co-signed at a bank in Pune so you could do the master's degree tha
One W-2 earner. One spouse on an H-4 with no work authorization, or with an approved H-4 EAD and no job yet. A car each, a couple of credit cards, and a preapproval letter that came back smaller than
Your loan officer emails you a one-line update and it contains a word you have never seen used this way: Refer. Not denied. Not approved. Refer.
That word is the automated underwriting system telling
Six months. That is the earliest a FICO score can exist for you, and almost nobody arriving in this country is told that on day one. They get told "build credit," which is advice the way "get in shape
No. Your CIBIL score does not work in the United States.
You deserve that in the first line instead of four paragraphs down. But the reason matters, because it tells you exactly what to do next — and
The L-1 transferee arrives in a strange position. You have eight years at the same multinational, a title that took a decade to earn, a salary that puts you comfortably in the top decile of your new z
Twelve years. That is the sort of wait an EB-2 or EB-3 India filer is quoted when they ask their attorney about a priority date, and it converts "wait for the green card" from a strategy into a decisi
Ask around at a Diwali party and someone will tell you about a cousin who lost his job, lost his status, and lost his house to the bank. That story is the single most expensive misunderstanding in thi
A borrower in Irving sent his lender a photo of his visa stamp on a Tuesday. On Thursday the processor asked for the I-94. The following Monday, the I-797. Two weeks later, underwriting wanted the bac
There are three boxes in Section 1 of the Form 1003, and ticking the wrong one is not mortgage fraud. Misrepresenting which one is true is a different matter entirely. Yaar, most borrowers we talk to
You are looking at an I-797A with a validity end date four months out. Your extension was filed in June. Your realtor sent three listings this morning and you have not opened them, because someone tol
Same borrower. Same W-2s. Same 748 score. Same I-797. Declined on a Tuesday, approved on a Thursday, by two lenders eleven miles apart.
Nothing about the file changed. What changed was whose credit po
Three phrases get used as if they were synonyms. "Non-citizen." "Non-resident alien." "Non-permanent resident." Borrowers swap them freely, and so do plenty of loan officers.
They are not synonyms. Th
Your loan officer called back and said your O-1 "isn't on the approved list."
Ask him to send you the list.
He will not send it, because it does not exist. Fannie Mae has never published a roster of a
On March 26, 2025, HUD issued Mortgagee Letter 2025-09. One sentence in it ended FHA financing for every H-1B, L-1, O-1 and TN holder in the United States:
"This ML removes the Non-permanent Residents
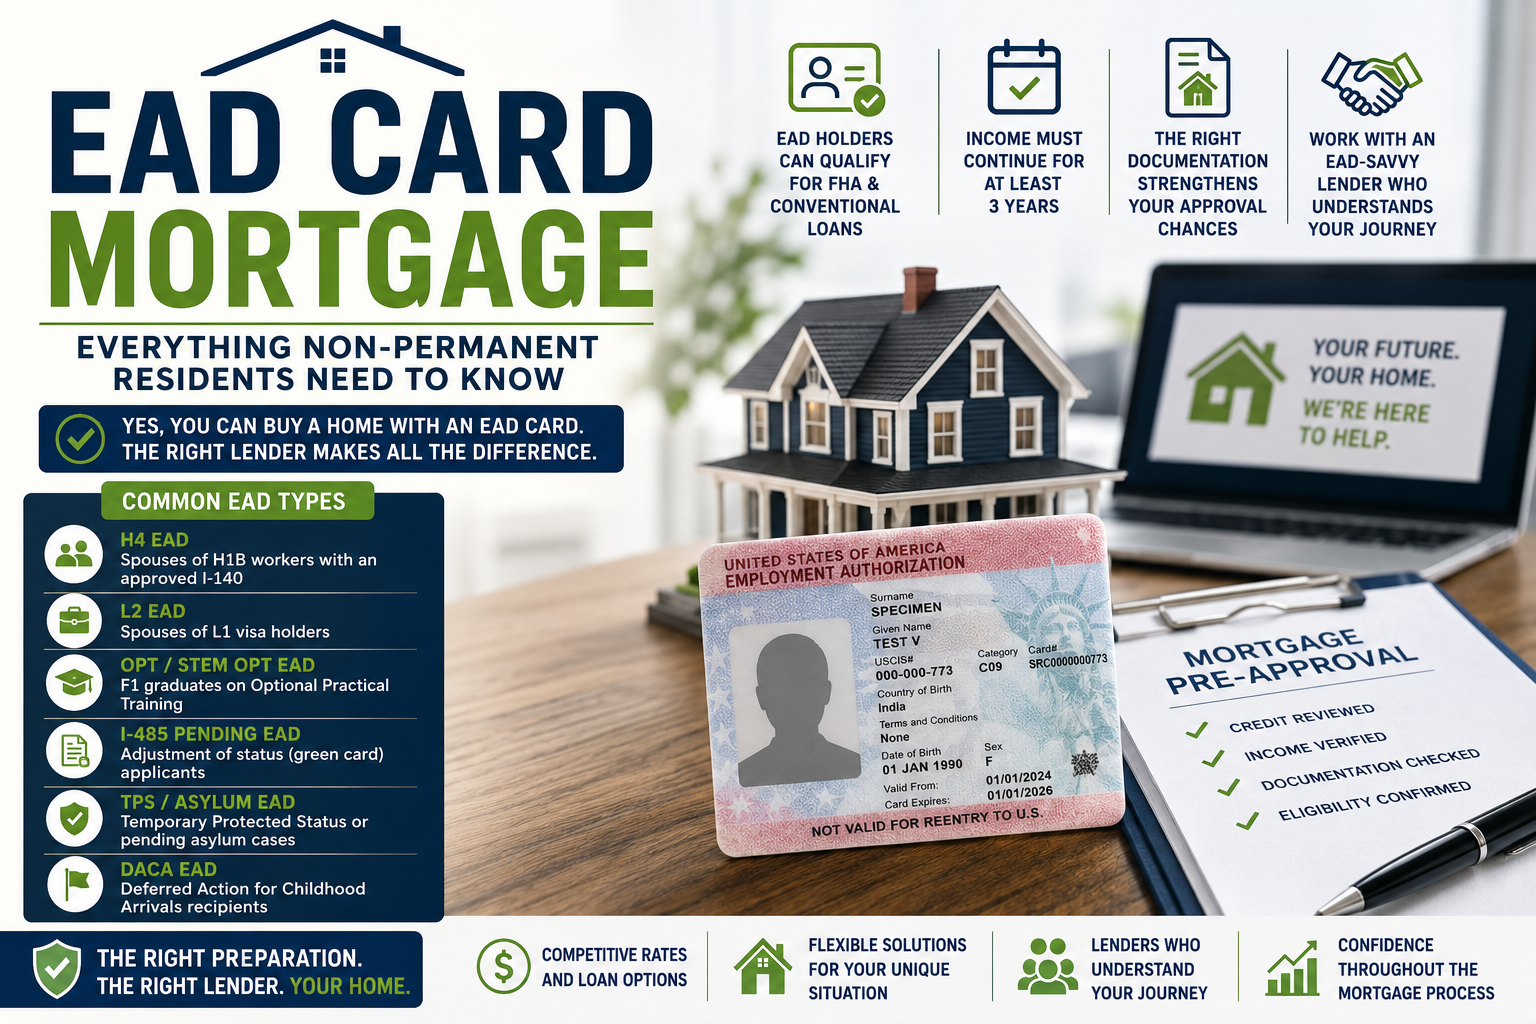
Your Employment Authorization Document — the plastic card in your wallet that says you’re legally allowed to work in the United States — is not a barrier to homeownership.
But depending on which type
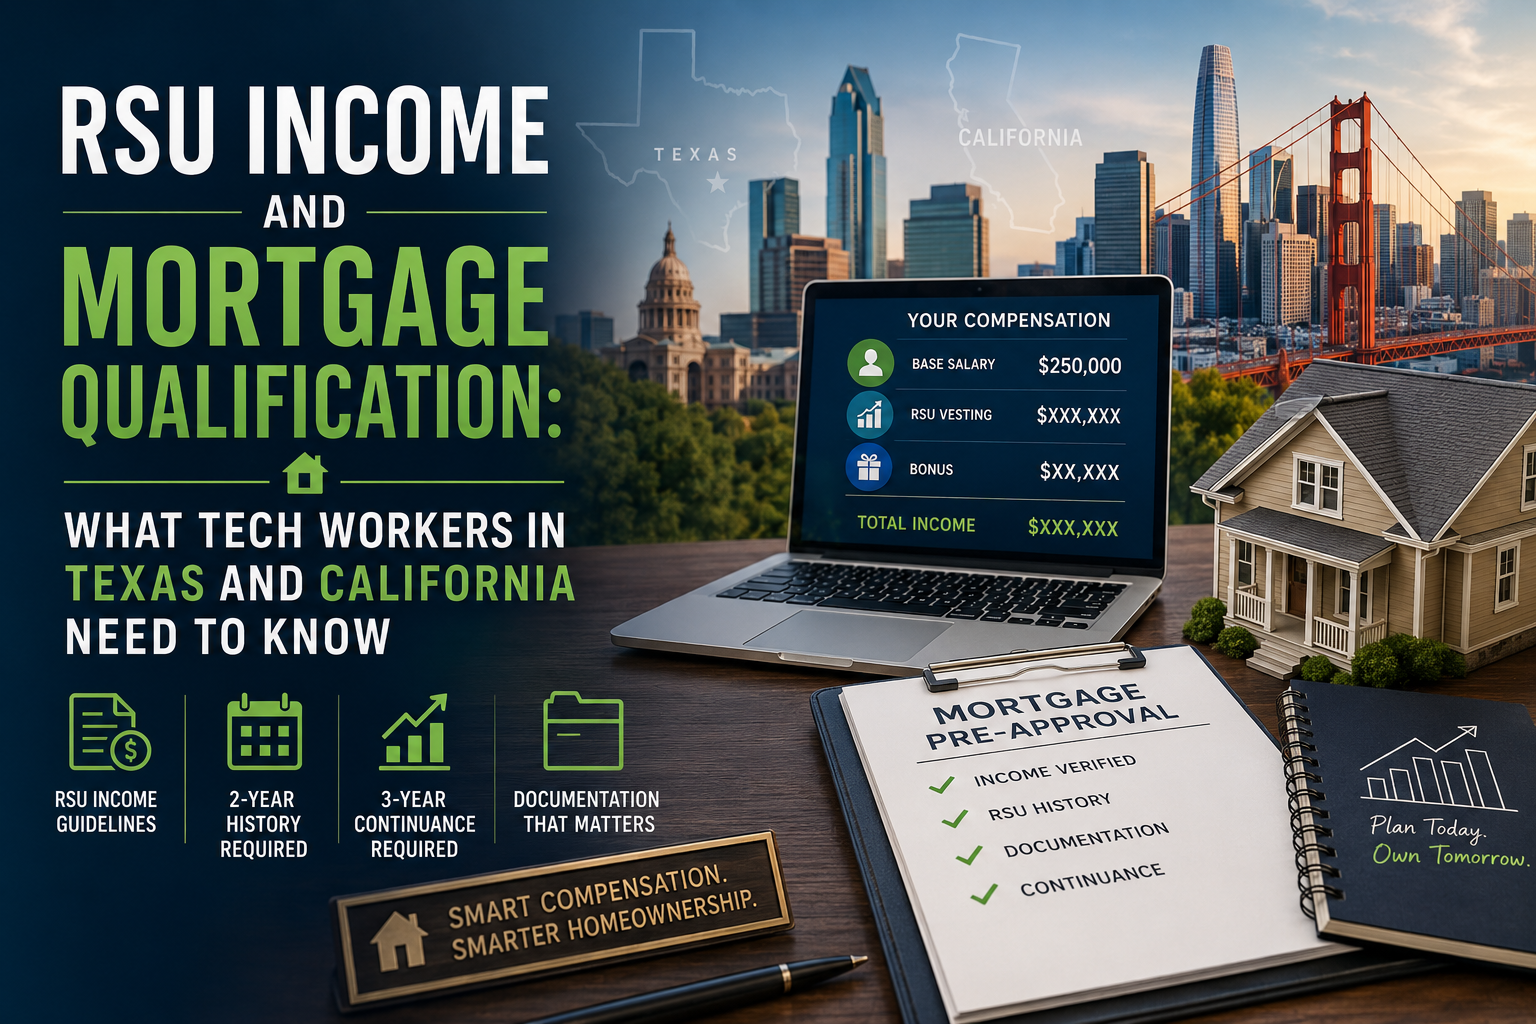
You make $250,000 a year. A third of that is RSUs. Your base salary alone puts you in a comfortable bracket, but it’s the vesting stock that makes you feel, as the kids say, built different.
Then you
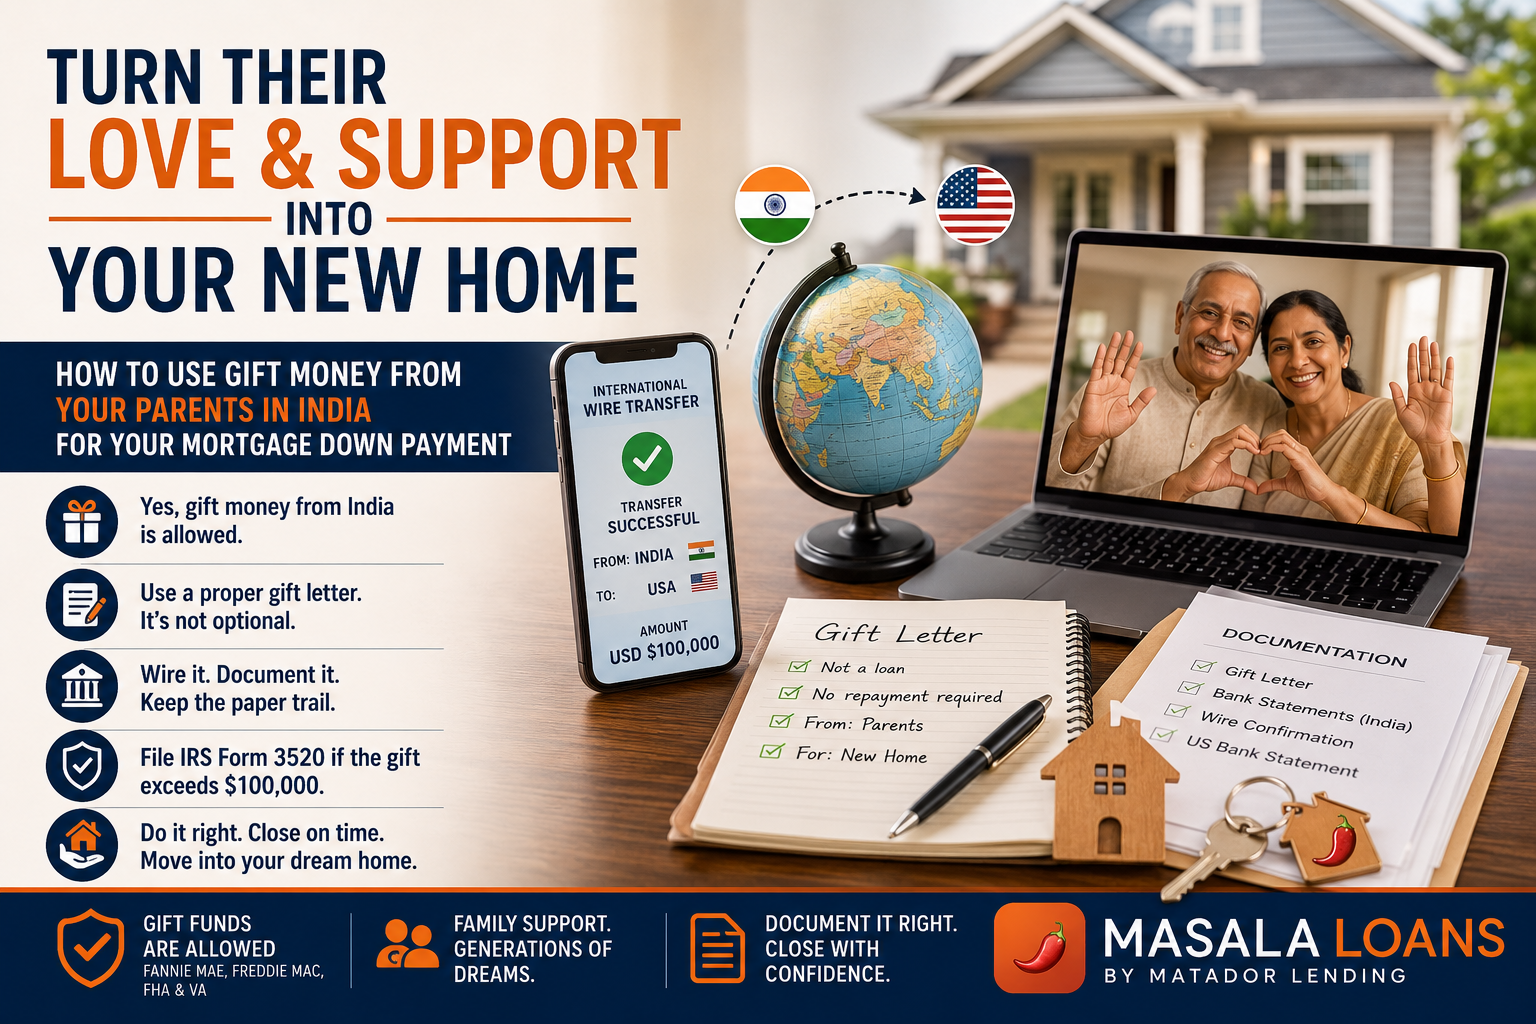
Beta, we bought your down payment. Now go buy a house.
If you’ve had this conversation — or are about to — you’re not alone. Across the South Asian diaspora in America, family wealth flows across the
Yes. Full stop.
You can absolutely get a mortgage on an H1B visa in 2026. The idea that you need a green card or citizenship to buy a home in the United States is one of the most persistent myths in t